W-2 vs 1099: What Small Business Owners Need to Know

SMALL BUSINESS INTEL, IN YOUR INBOX
Table of contents
You’re adding help for a busy stretch: a server to cover weekend shifts and a freelancer to photograph your new menu. Do both go on payroll, or does one get a 1099? The answer depends on how the work happens, not on which option is easier for your books. Get it wrong and you could owe back payroll taxes, penalties, and interest.
Here’s how W-2 and 1099 workers differ, how each is taxed, what each costs at an hourly wage, how the IRS and the Department of Labor (DOL) decide, and what changed in 2026. This is general guidance, not legal or tax advice.
W-2 vs 1099 at a Glance: The Short Answer
- W-2 employees: You direct the work, withhold their taxes, and pay half of their Social Security and Medicare (7.65%).
- 1099 contractors: Typically, they run their own business, decide how the work gets done, and pay their own taxes.
- The test: The full working relationship decides it, not the contract label.
- New in 2026: The 1099-NEC reporting threshold rose from $600 to $2,000 for payments made in 2026.

W-2 vs 1099: The Main Differences
The main difference between W-2 and 1099 workers is the working relationship. A W-2 employee typically works under your direction, and you withhold their taxes and pay the employer share of payroll taxes. A 1099 contractor typically runs their own business, chooses how to do the work, and pays their own taxes.
No single row below decides classification. Treat the table as a general guide.
| Factor | W-2 employee | 1099 contractor |
|---|---|---|
| Who controls the work | Typically you direct how, when, and where | Typically they decide their own methods |
| Tax withholding | You generally withhold income tax and the employee’s 7.65% FICA share (Social Security and Medicare), and pay your own 7.65% | They handle their own income tax and self-employment tax, unless backup withholding applies |
| Self-employment tax | Not applicable | Generally 15.3% on 92.35% of net profit (the Social Security part stops at the annual wage base) |
| Benefits and protections | Employer taxes, insurance, and wage rules apply under federal and state law; benefits vary | No employer benefits or payroll taxes, but contract terms vary, and a misclassified worker may be owed employee protections |
| Tools and equipment | Often provided by you | Often their own |
| First paperwork | Form W-4 and Form I-9 (plus state forms) | Form W-9 |
| Year-end form | W-2 | 1099-NEC for qualifying payments of $2,000 or more in 2026 (backup withholding can require one below that) |
| Examples that often fit | Ongoing, core work | Project-based, specialized, or seasonal work |
What Is a W-2 Employee?
A W-2 employee typically works under your direction. You often set the schedule, provide the training and tools, and decide how the job gets done. They can be full-time, part-time, or seasonal.
In return, you withhold their federal income tax (and state and local tax where required) and pay half of their Social Security and Medicare taxes. That’s 7.65% from you and 7.65% from them, the two halves of the 15.3% Federal Insurance Contributions Act (FICA) tax. You also generally pay federal and state unemployment taxes, and carry workers’ compensation where your state requires it.
At year-end, you file a Form W-2 for each employee reporting wages paid and taxes withheld. The 2026 form includes new reporting fields: cash tips (Box 12, code TP), qualified overtime (Box 12, code TT), and tipped occupation codes (Box 14b). Code TT covers only the qualified overtime premium, such as the extra half in time-and-a-half, not all overtime pay.
What Is a 1099 Contractor?
A 1099 contractor is self-employed. They often use their own tools, set their own hours, and can work for several clients at once. You’re one of their clients, not their employer.
You may hear people say “1099 employee,” but that’s an informal phrase, not a legal category. Use “independent contractor.”
You generally don’t withhold payroll taxes from contractors, unless backup withholding applies. That’s tax you hold back when a payee hasn’t given you a valid tax ID. Contractors pay their own income taxes plus self-employment tax, generally 15.3% on 92.35% of net profit. That covers both halves of Social Security and Medicare.
Collect a Form W-9 before the first payment so you have their tax ID. For payments made in 2026, you file a Form 1099-NEC when you pay a contractor $2,000 or more for services. That’s up from $600, and the threshold may adjust for inflation starting in 2027.
Backup withholding can still require a form below $2,000. This is a reporting threshold only. It doesn’t decide whether someone is a contractor or an employee.
W-2 vs 1099 Taxes: What You Owe as an Employer
Do 1099 Contractors Pay More Taxes Than W-2 Employees?
It depends on the tax. Contractors generally pay both halves of Social Security and Medicare through the 15.3% self-employment tax, while a W-2 employee pays 7.65% and the employer pays the other half. Their total tax bill depends on income and deductions, since contractors can deduct business expenses.
Contractors generally must make estimated tax payments if they expect to owe at least $1,000 after withholding and refundable credits and don’t meet the applicable IRS withholding and estimated-payment requirements. Exceptions apply. If you’re new to employment taxes, our small business taxes for beginners guide is a good place to start.
2026 Deadlines and Filing Rules for W-2s and 1099s
- W-2 withholding: Withhold federal and state income taxes each pay period and pay your share of FICA.
- Federal unemployment tax (FUTA): The standard rate is 6.0% on the first $7,000 of each employee’s wages, generally reduced to 0.6% when you get the full state credit. Businesses in credit-reduction states can owe more.
- Deadline: Forms W-2 and 1099-NEC for 2026 are due February 1, 2027, because January 31 falls on a Sunday.
- E-filing: If you file 10 or more W-2s, 1099s, and similar forms in total, you must file electronically unless you qualify for an exception or waiver.
- Contractors: Collect a W-9 first and keep invoices all year. They handle their own estimated taxes.
Year-end is where payroll fees can stack up. Your current provider may charge per W-2 and 1099, and you file a W-2 for everyone who worked for you this year, including people who’ve left. We offer free electronic W-2s, and our payroll experts handle the transfer, filings, and setup in under a week. Features vary by plan and state, and you’re still responsible for accurate, on-time filing. Our guide to payroll forms covers what each one is for, and you can see how Homebase payroll handles them.
How the IRS and DOL Decide Whether Someone Is a W-2 or 1099 Worker
There’s no single test. The IRS, the DOL, and state agencies each use their own, and they don’t always agree.
The IRS Three-Factor Test
The IRS looks at three areas together:
- Behavioral control: Do you control, or have the right to control, how the work gets done, including hours, training, and methods?
- Financial control: Does the worker invest in their own tools, bear unreimbursed expenses, and have a chance at profit or loss?
- Type of relationship: Is the work ongoing and central to your business? Do they get employee-type benefits? What does the contract say?
No single answer settles it, and a contract label or a 1099 form can’t override how the work happens. The IRS guidance on employees and independent contractors walks through each area. Kris Herbert, owner of The Gym Venice in Venice, California, offers one owner’s rule of thumb:
“You can’t have independent contractors performing the same service that your business performs.”
It isn’t a universal legal rule, since the tests depend on the law that applies and the full relationship.
The DOL’s Classification Test in 2026
The DOL announced a proposed rule on February 26, 2026, and the Federal Register published it on February 27. It would replace the 2024 rule’s analysis with a modified version of the 2021 framework. That framework weighs five factors. Two get the most weight: control over the work, and the worker’s opportunity for profit or loss based on initiative or investment. The other factors still count.
As of late October 2026, the proposal isn’t final. Federal records show it under review at the Office of Information and Regulatory Affairs for possible final action. Separately, in May 2025 the DOL told its investigators not to apply the 2024 rule’s analysis while it reviews that rule. The regulation itself hasn’t changed, and employers can still face private claims and state rules.
State ABC Tests
California, Massachusetts, and New Jersey use an ABC test in certain contexts. Under it, you generally have to show that the worker is free from your control, does work outside your usual business, and runs an independent business of their own. The details and the laws covered differ by state, so a federal classification and a state classification can come out differently. New Jersey’s clarified ABC rules took effect October 1, 2026, and cover specified New Jersey labor laws.
California Labor Code Section 226.8 sets civil penalties of $5,000 to $15,000 per violation for specified misclassification practices, and $10,000 to $25,000 when there’s a pattern or practice. These aren’t automatic penalties for every classification mistake. Check the independent contractor laws for your state before you hire.
What to Do if You’ve Misclassified a Worker
Misclassification can lead to back payroll taxes, penalties, and interest, plus wage and state liabilities, depending on the facts. Maryland’s 2025 enforcement report shows how active this area is. Participating agencies identified 7,767 misclassified workers, and the state’s unemployment insurance division identified more than $174 million in unreported wages. That’s unreported wages, not unpaid tax.
You have two ways to start fixing it:
- Form SS-8: Ask the IRS for an official determination of whether a worker is an employee or a contractor.
- Voluntary Classification Settlement Program (VCSP): Eligible employers can reclassify workers going forward and get specified federal employment-tax relief. You generally must have treated the workers as contractors consistently, filed the required 1099s for the past three years, and not be under certain audits.
Neither is an amnesty, so talk to a tax professional first. Homebase HR Pro gives you access to HR professionals, policy reviews, and alerts about federal and state labor-law changes. It isn’t legal advice, so bring serious legal questions to a lawyer. You can read more about HR and compliance in the app.
What a W-2 Employee Costs vs a 1099 Contractor
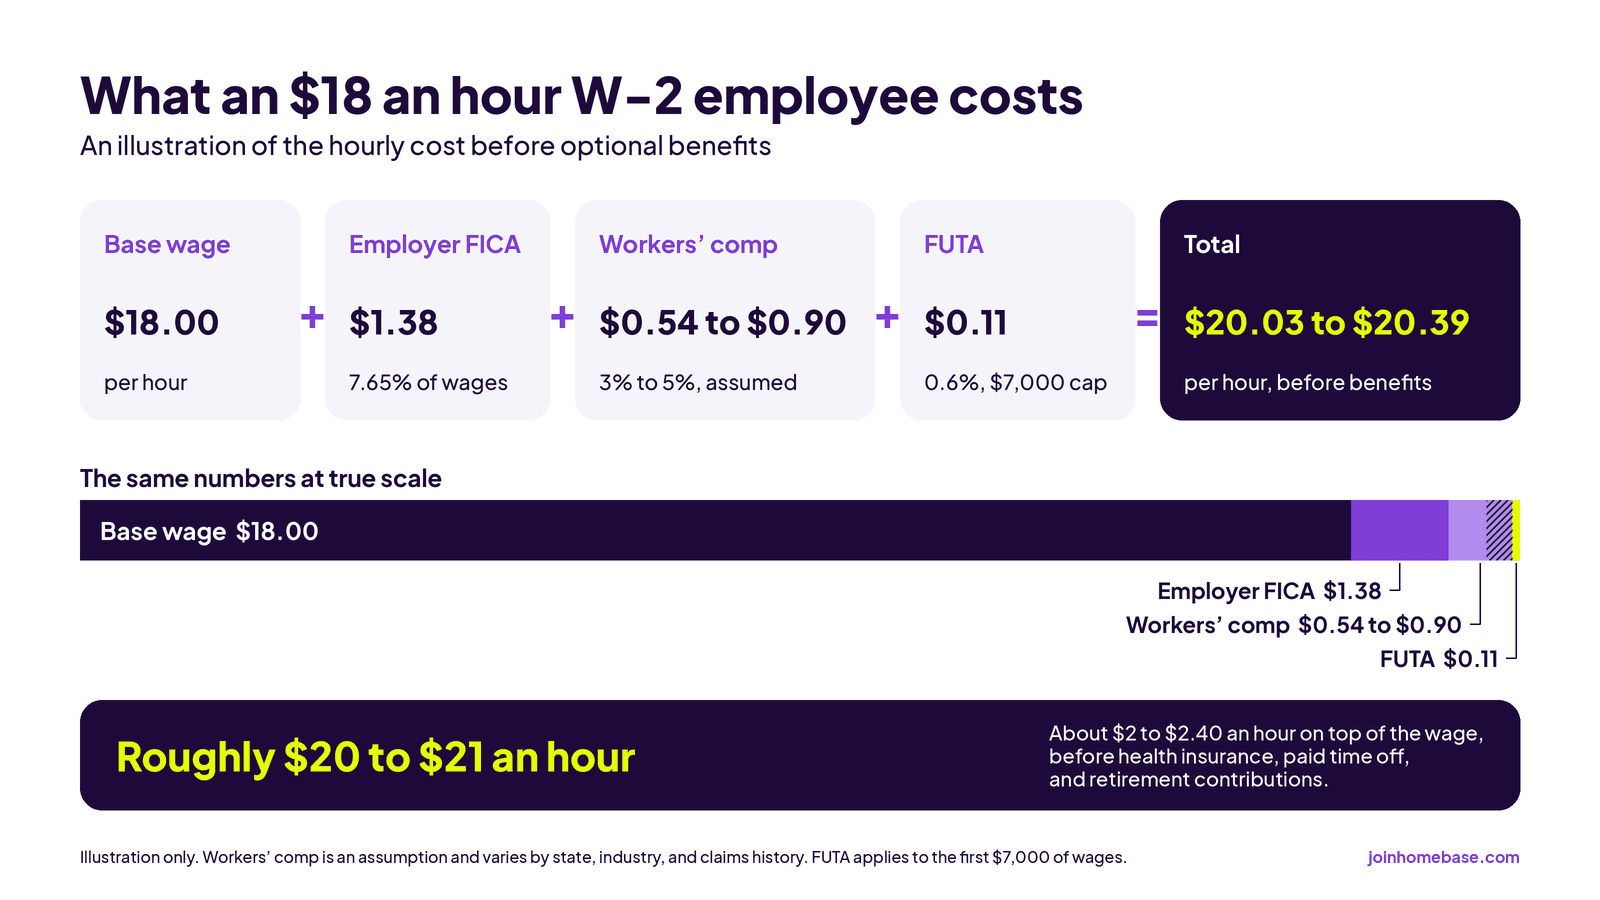
If you run a restaurant, shop, or salon, you’re thinking in dollars per hour, not salaries. Here’s an illustration for an employee earning $18 an hour:
- Base wage: $18.00
- Employer FICA (7.65%): $1.38
- Workers’ compensation (3% to 5% assumed): $0.54 to $0.90
- FUTA (about 0.6% of wages, up to the $7,000 cap): about $0.11
That adds up to $20.03 to $20.39 an hour before optional benefits like health insurance, paid time off, and retirement contributions. We’re rounding to roughly $20 to $21. Your actual cost can fall outside that range. Workers’ comp premiums vary by state, industry, job classification, and claims history, so treat that line as an assumption and check your own quote.
For a properly classified contractor, you generally don’t pay employer payroll taxes on what you pay them. You may still cover expenses, supplies, insurance, or contract benefits, and their rate may be higher because they cover their own taxes and insurance. Compare the total cost over the length of the project, not the hourly rate alone.
Ongoing work you schedule often fits W-2. Project-based, specialized, or seasonal work often fits 1099, like a photographer for a menu shoot. These are examples, not legal tests, and the working relationship decides. For the other costs first-time employers miss, see our guide to the true cost of a new employee.
Examples of W-2 vs 1099 Workers in Small Businesses
Job titles alone don’t decide classification. These are common patterns, not rules.
Roles that are often W-2:
- A server you schedule for shifts.
- A retail associate who works your store hours.
- A barista who clocks in and out with your team.
- A front desk employee at a salon or medical office.
Roles that can be 1099:
- A freelance photographer for your spring menu shoot.
- A bookkeeper who handles your quarterly taxes.
- A web developer building your online ordering page.
- A catering contractor for a one-time event.
The line blurs when someone works ongoing hours doing your core work while being called a contractor. Picture a “freelance” server who works every Friday and Saturday, uses your equipment, and follows your house rules. Those facts point toward an employment relationship.
The Gym Venice started out with contractors, then switched its trainers to W-2s. Kris Herbert says the change made tracking hours more important and payroll easier:
“Since switching [my trainers] to W-2s, accurate time tracking is really important. Running payroll has definitely been easier with their hours and sessions all synced. It feels good knowing I’m being compliant.”
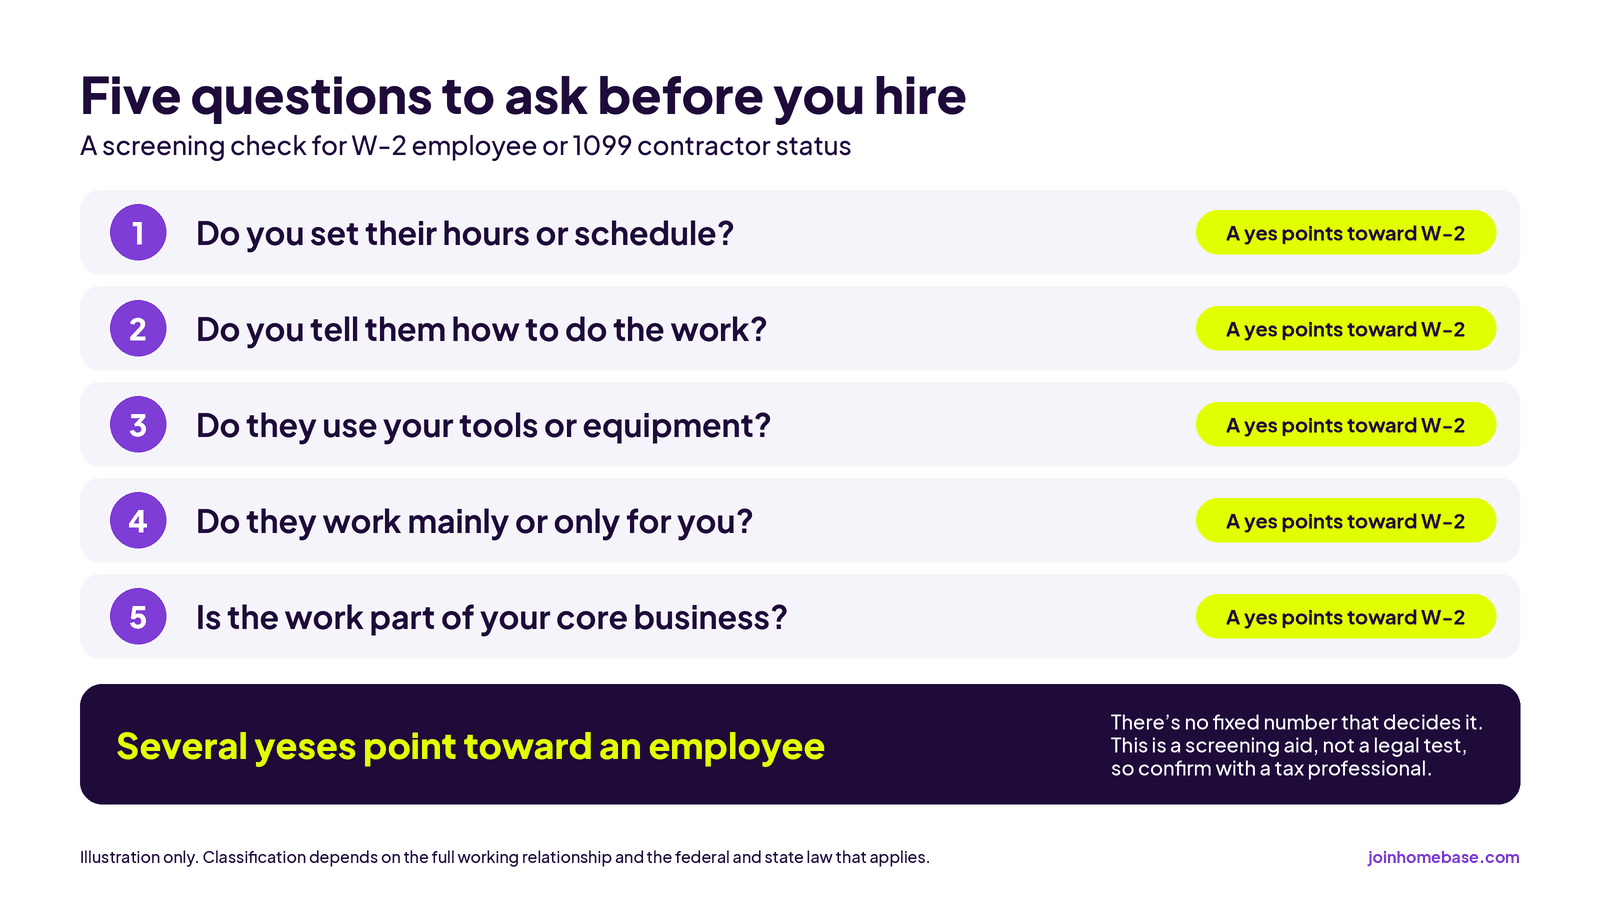
A quick screening check before you hire. Ask yourself:
- Do you set their hours or schedule?
- Do you tell them how to do the work?
- Do they use your tools or equipment?
- Do they work mainly or only for you?
- Is the work part of your core business?
Several yeses point toward an employee, but there’s no fixed number that decides it. This is a screening aid, not a legal test, so confirm with a tax professional.
How to Pay and Manage W-2 Employees and 1099 Contractors
For W-2 employees, set a steady pay schedule and keep accurate time and pay records. Employers covered by the Fair Labor Standards Act (FLSA) must keep required records. Our guide to the best payroll schedule for hourly workers covers the trade-offs.
For contractors, agree on rate and payment terms first, then pay on invoices. If you’re hiring one, see how to hire an independent contractor.
Paperwork for W-2 employees:
- W-4 for tax withholding.
- I-9 for work eligibility.
- State and local tax forms.
Paperwork for 1099 contractors:
- W-9 with their tax information, collected before the first payment.
- A written contractor agreement. It helps, but it doesn’t establish contractor status on its own.
- Invoices for every payment.
- Annual totals for each contractor.
Riley McGuire, Director of HR at Student Agencies, runs both worker types in one place:
“I also think it’s really helpful to have independent contractors and full-time employees within the same system and within the same payroll and everything because you can send them different documents and it’s really easy to keep track of all of that within Homebase since it is like super flexible.”
Homebase supports online onboarding for employee tax and work-eligibility forms, including W-4s and I-9s, and for contractor tax forms, including W-9s. Direct deposit setup is also available. The broader digital onboarding packet, with e-signatures and secure document storage, is listed under the All-in-One plan.
Classify Your Workers Correctly Before Payday
Classification is easier to get right before the first paycheck than after. Three things to take with you:
- The full relationship decides it. A contract that calls someone a contractor doesn’t make them one.
- 2026 brought changes. The 1099-NEC reporting threshold is now $2,000 for qualifying payments made in 2026, and the DOL’s proposed test isn’t final yet.
- The cost isn’t only the rate. Payroll taxes, workers’ comp, and benefits can move an employee’s true cost well above their hourly wage.
Making your first hire? You can set up and run your first payroll in one day. Already paying your team somewhere else? Switching takes about 20 minutes of your time, and our payroll experts handle the rest. Chat with our payroll advisors.
Frequently Asked Questions About W-2 vs 1099
What Is the Difference Between a W-2 and a 1099?
A W-2 employee typically works under your direction while you withhold their taxes, match their Social Security and Medicare, and file a W-2. A 1099 contractor typically runs their own business and pays their own taxes. You report qualifying contractor payments on a 1099-NEC at $2,000 or more in 2026. The form follows the classification, not the reverse.
Is W-2 the Same as 1099?
No. A W-2 reports wages paid to an employee and the taxes withheld from them. A 1099-NEC reports qualifying nonemployee compensation, such as payments to an independent contractor, with no withholding. The form follows the working relationship, so the right one depends on the full facts, not on which form is easier to file.
Do You Pay More Taxes on a 1099 or W-2?
It depends on the tax. Contractors generally pay both halves of Social Security and Medicare through the 15.3% self-employment tax, while a W-2 employee pays 7.65% and the employer pays the other half. Contractors can deduct business expenses, so their total tax bill depends on income and deductions. Some raise their rates to cover the difference.
What Are the Downsides of Being a 1099 Contractor?
Independent contractors generally don’t get employer benefits or employee unemployment coverage, so they typically buy their own health insurance and cover both halves of Social Security and Medicare. Income can swing between projects. Estimated tax payments are generally required when they expect to owe $1,000 or more after withholding and credits. Contractor rates may be higher for these reasons.
How Much More Does a W-2 Employee Cost Than a 1099 Contractor?
For an employee earning $18 an hour, employer FICA, assumed workers’ comp, and FUTA add roughly $2 to $2.40 an hour, and optional benefits add more. A contractor’s invoice is the main cost, but you may also cover expenses or supplies, and their rate may be higher to cover their own taxes and insurance. Actual costs vary.
Can Someone Be Both a W-2 Employee and a 1099 Contractor?
Yes, when the arrangements are clearly separate. A salaried manager who also photographs your menu for a flat fee is one example. If the services overlap or look the same, the arrangement needs careful review and often points to employment. Talk to a tax professional before you pay someone both ways.
What Happens if You Misclassify a Worker?
The IRS can assess back payroll taxes, penalties, and interest, depending on the facts. The Department of Labor can pursue back wages and overtime, and state agencies may add their own penalties. Not every case brings every consequence. The IRS Voluntary Classification Settlement Program offers some eligible employers a way to reclassify workers going forward with tax relief.
What if My Employer Gave Me a 1099 Instead of a W-2?
If you work set hours, use your employer’s tools, and have no other clients, you may be misclassified. You or your employer can file IRS Form SS-8 to request an official determination. Whether you can adjust past taxes depends on the facts, so talk to a tax professional before you file anything.
Run payroll for employees and contractors in one place
Whether you’re making your first hire or paying a mix of employees and contractors, Homebase keeps the pay, tax forms, and paperwork together. Our payroll calculates and files your taxes, and we offer free electronic W-2s at year-end.
Starting from scratch? You can set up and run your first payroll in one day. Already paying your team somewhere else? Switching takes about 20 minutes of your time, and our payroll experts handle the transfer, filings, and setup in under a week.